Readers researching medical billing after a car accident need practical distinctions, reliable sources and a clear next step. The answer often depends on the circumstances, what can be verified and which professional or official instructions apply. This accident claims & insurance guide focuses on the decision points people can actually investigate, rather than promising a universal result.
It is easy to focus on an insurer’s first answer or a single legal term, but the useful questions are more specific: what happened, which rules apply, what evidence survives, and what deadlines are approaching? This guide explains the practical distinctions without claiming that the result of any individual case is predetermined.
Why medical bills and injury claims are separate workflows
Medical billing after a car accident can continue long after a vehicle is repaired. A patient may receive an emergency department bill, an insurance explanation of benefits, an ambulance statement and a repayment notice from another organization. These documents serve different purposes. Sorting them by provider, payment source and legal basis is more useful than assuming the total outstanding figure is the final amount owed. An accurate timeline matters more than a dramatic description. Record what was known on the day, what became clear later, and who supplied each piece of information. An insurance position or police summary is not automatically the final legal finding. Keep originals, preserve uncertainty, and do not guess at missing details. For further context, review Accident Advocate resources.
A health insurer, an auto insurer offering medical-payments coverage, an employer-sponsored plan and a government program may each have different rules. Which coverage applies can depend on location, policy wording and the facts of the crash. One person’s experience with a particular settlement cannot establish another claimant’s rights. Read the documents and ask for precise explanations. Before relying on any general rule, check which jurisdiction, deadline, coverage agreement, and type of claim actually applies. A useful article should separate a possible legal theory from proof that its elements are satisfied. A legal professional can review whether exceptions or procedural prerequisites change the analysis.
Identify which insurer paid each charge
Subrogation broadly refers to circumstances in which an insurer asserts rights connected with an amount it paid. A lien may describe a legally recognized claim against proceeds, but the term is sometimes used loosely in letters. Whether reimbursement is permitted and how much is due depend on state law, plan terms and the nature of the payment. Do not assume every demand is enforceable. Build a folder containing dated photographs, correspondence, relevant policy pages, receipts, and a simple index. Save originals separately from annotated copies. A consistent record can help an independent reviewer understand the event without assuming that one screenshot or one witness statement tells the entire story.
Health insurance and medical-payments coverage differ
Ask each provider for itemized charges and a record of payments and adjustments. Compare the service date against the incident and confirm whether a claim has been filed with health insurance. Duplicate statements may reflect processing changes rather than separate new treatment. Keep original billing documents while you request correction of possible errors. Consider what an opposing explanation would look like. Were there multiple contributing causes, conditions that changed over time, or documents pointing in different directions? Testing a claim against those alternatives produces a more reliable picture than choosing the first explanation that feels intuitively correct.
An unpaid bill is not automatically a valid lien
Public programs often have specific notice and recovery procedures. For example, California’s Medi-Cal Personal Injury Program publishes rules governing potential reimbursement from third-party settlements. That California example should not be applied automatically to a case in another state. Identify the governing agency and jurisdiction before using any deadline or calculation. Avoid sharing sensitive records publicly or submitting unnecessary personal identifiers through unverified forms. Contact organizations through verified channels, document what was requested, and preserve confirmation numbers. Online resources can explain a process, but only a qualified professional who reviews your facts can advise on a particular case.
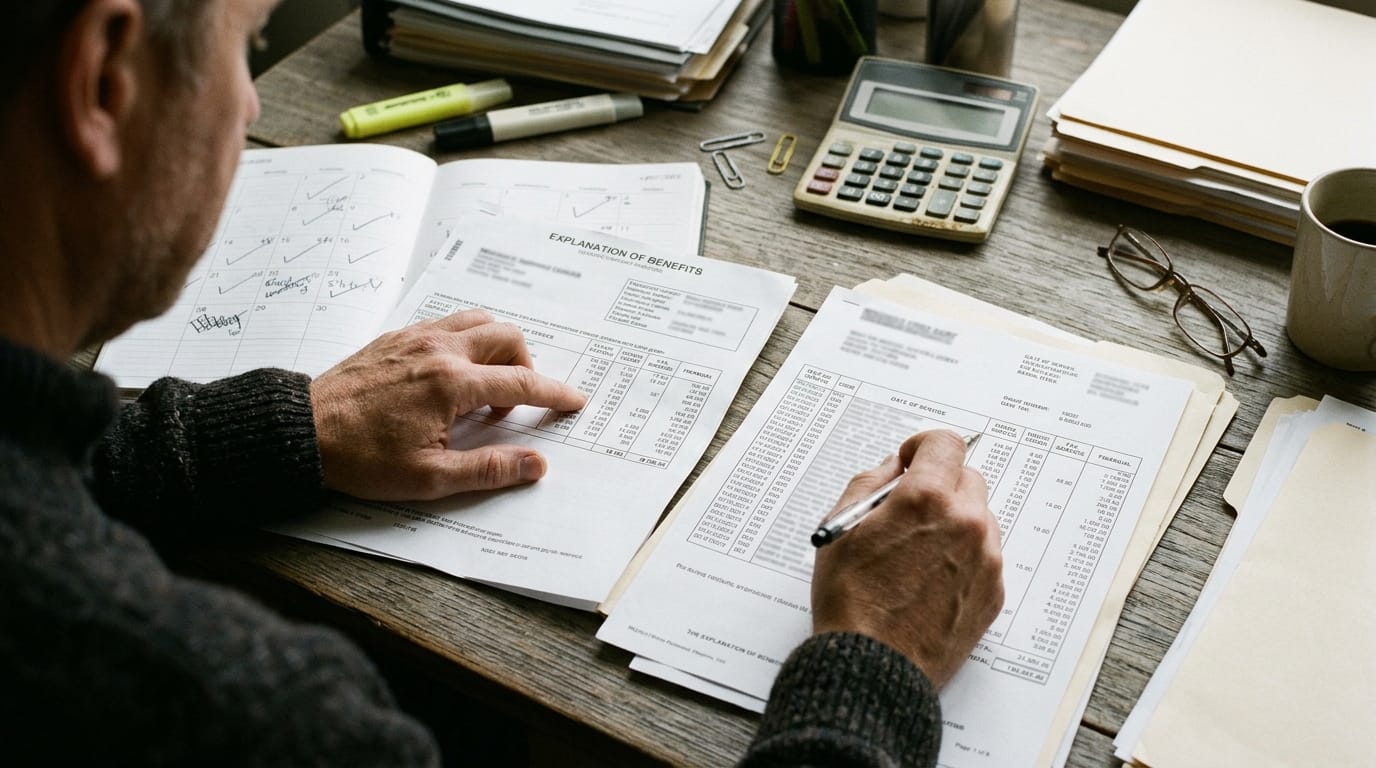
An explanation of benefits is often marked ‘not a bill.’ It can show what a health plan processed without demanding payment from the patient. Compare its figures with the actual provider invoice and plan correspondence. This one distinction prevents many misunderstandings about apparent duplicate charges.
Understand liens and subrogation without assumptions
Medical providers may seek payment directly from patients even as an injury claim remains disputed. Ask about balances, collection status and billing holds, but avoid relying on an oral promise that a bill will disappear when a lawsuit ends. Keep records of every arrangement and obtain professional review of agreements that assign settlement proceeds. A single day rarely captures the whole consequence of an accident. Treatment may evolve, repairs may reveal hidden damage, and an employer may need updated work restrictions. Maintain dated records without exaggeration, and do not sign a broad release until the financial and legal implications are understood.
The word ‘lien’ may appear in correspondence before the amount has been fully calculated. Ask who asserted it, which payments are included and how the amount will be finalized. Different payers may have different procedures for reductions or disputes, so a one-size-fits-all template is unreliable.
How to organize bills and reimbursement demands
A settlement calculation should begin with the gross recovery and then show approved fees, case expenses, valid reimbursements and the amount actually available to the claimant. Disputes can arise over what treatment was related to the accident or what reduction is authorized. Accurate records and legal advice matter more than a simple percentage guessed from the gross figure. When there are conflicting statements, compare their timing and sources rather than labeling one person dishonest. Identify photographs, recordings, electronic records, and independent observations that may resolve the difference. Evidence is strongest when it is preserved lawfully and can be traced to its original source.
Avoid settlement surprises
When contacting billing offices, use a dated log with provider name, claim reference, amount discussed and promised next step. Send only the information necessary to resolve the question through secure channels. A single consolidated spreadsheet helps identify which bills are pending with insurance and which require a response from the claimant. Write a short list of questions before speaking with a claims handler, agency, or lawyer. Ask which documents are missing, what response deadlines apply, and how decisions will be communicated. Keep a record of the answer and request important explanations in writing when practical.
Request the legal basis for a claimed repayment
Imagine three bills for the same emergency visit: the hospital facility, emergency physician and radiology service. That does not necessarily mean the patient was billed three times for the same exact work. Compare service codes, dates and payer explanations before disputing or paying. The goal is correct accounting, not an assumption that every unfamiliar charge is improper. No article can promise a settlement amount or outcome. Legal standards, evidence, insurance contracts, and individual circumstances control the analysis. Use the guidance here as a preparation checklist, and seek case-specific advice before deadlines expire or a final agreement is signed.
Check the net settlement before accepting
If treatment is ongoing, an early settlement may leave uncertainty over future costs. Discuss that risk with counsel and clinicians rather than treating a present snapshot as a final prognosis. A claim’s gross number means little without a realistic understanding of the liabilities and expected care associated with it.
A good billing summary can show four columns: provider, amount billed, payment adjustment and amount currently disputed. Add the source document and date for each row. This creates a clear view without assuming that the largest figure is the actual obligation. Review it again when new insurer payments or correction notices arrive.
Quick reader check: Is the decision based on the correct jurisdiction? Are source documents preserved? Is an important assumption being presented as certain? Which deadlines are confirmed, and which still need verification? These four questions can identify avoidable gaps before an insurer, agency or attorney makes a consequential decision.
For authoritative context, consult California DHCS Personal Injury Program example. Its scope and limitations should be considered alongside the specific facts; the link is not a substitute for professional or local instructions.
The best next step is a clear file and an accurate set of questions. Separate documented facts from assumptions, verify the governing deadlines and seek advice from a qualified professional when legal rights or settlement obligations are at stake. This article is general information, not individual legal advice or an offer of representation.